Transatlantic Contraction Exposes the Limits of Outbound Asian Tourism
Slumping Western European visitor traffic leaves American destinations vulnerable despite incremental outbound recovery from China
SINGAPORE
Long-haul aviation runs on a straightforward mathematical equation: high-yielding transatlantic leisure seats historically underwrite route stability, absorbing operational overheads while secondary long-haul corridors build volume. When core feeder markets falter, network planning fractures. Preliminary figures released on Friday by the National Travel and Tourism Office show that inbound overseas arrivals to the United States dropped 4.3% in September to 2.7 million visitors. That contraction extends a deepening trajectory following a nearly 12% year-over-year decline in August, alongside disappointing inbound tallies in June and July that failed to gain durable traction even with World Cup visitors entering the country. Across the year to date, overseas arrivals have fallen 5.7%.
Market watchers tracking outbound Asian departures often treat cross-Pacific travel as an inexhaustible reserve. Recent performance dismantles that assumption. Gains recorded from China and South America have proved insufficient to counterbalance the sustained retrenchment from Western Europe. For hospitality operators, destination marketing authorities, and commercial aviation desks across both hemispheres, this arithmetic alters revenue expectations. The underlying problem is not merely headcounts but the commercial yield profile of the missing arrivals.
Shifting Yields and Long-Haul Margins
Corporate balance sheets in commercial hospitality rely on length of stay and discretionary on-property expenditure. Western European travelers historically booked extended multi-city itineraries, sustaining urban center hotel occupancies and secondary regional circuits during peak holiday windows. A contraction among these travelers cannot be repaired through sporadic replacement volume. While outbound groups and independent travelers departing China are gradually returning to international networks, their volume and booking schedules cannot instantly plug transatlantic deficits. Replacing a two-week European holiday with short-stay arrivals creates churn rather than sustained RevPAR stability.
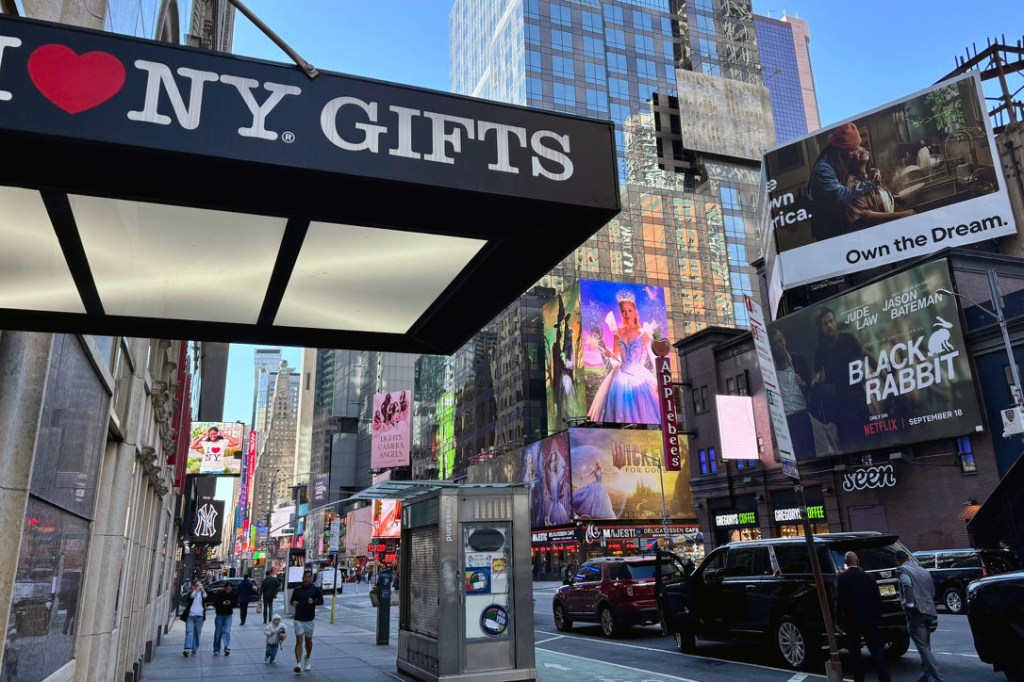
Gains from China and South America haven't been enough to make up for declines in travel from Western Europe.
This structural mismatch creates immediate operational consequences. Long-haul aircraft deployed on transpacific sectors require predictable cargo holds and premium-cabin load factors to remain profitable at current operating costs. When arrival tallies fall across consecutive peak summer months, network carriers re-evaluate capacity allocations. Aircraft scheduled between North American hubs and overseas gateways face pressure if inbound demand in North America softens overall network yields. Hoteliers from Times Square in New York City to primary metropolitan gateway corridors must reassess baseline occupancy projections when summer peaks dissipate without delivering standard margins. Fixed overheads, from municipal labor contracts to capital servicing, do not compress simply because international leisure travelers decide to stay home.
Network Recalibration and Market Realities
Destinations across the broader Asia-Pacific region now watch this displacement with calculated self-interest. If long-haul outbound journeys to North American cities become less compelling or cost-prohibitive for European travelers, alternative destinations compete to capture those diverted itineraries. Regional beach resorts, Asian metropolitan corridors, and secondary transit hubs seek long-stay European travelers searching for relative purchasing power. Yet relying on diverted transatlantic demand remains fraught with operational friction. Extended flight routings and volatile overheads limit how fluidly leisure travelers pivot between hemispheres, leaving hoteliers exposed if anticipated replacement traffic fails to arrive.
Sustained inbound growth in the United States cannot depend entirely on compensatory surges from emerging or recovering Asian origins. Outbound recovery from China has its own pace, constrained by commercial flight frequencies, administrative processing schedules, and domestic travel preferences. Expecting Asian outbound traffic to single-handedly rescue transatlantic deficits misreads both market scale and traveler intent. Asian travelers are increasingly selecting short-haul regional alternatives that offer lower logistical friction and superior price-to-value equations.
Tourism planning frequently mistakes gross arrival numbers for structural health. When an anchor market like Western Europe steps back, the entire hospitality apparatus faces an unsettled ledger. Whether North American travel infrastructure adapts its cost structure to lower transatlantic volumes, or whether Asian outbound traffic eventually accelerates enough to shift the balance, remains the decisive equation facing long-haul network planners. Until that gap narrows, hotel properties and aviation carriers will have to discount or accept lower asset utilization.
Sources
Newsletter
Pacific Daily
A curated briefing from Thailand, Asia-Pacific and the world.