The Bangkok Stalemate Over Capital and Risk
Finance leaders meeting in Thailand face a structural clash between corporate spending on artificial intelligence and escalating sovereign borrowing costs.
BANGKOK
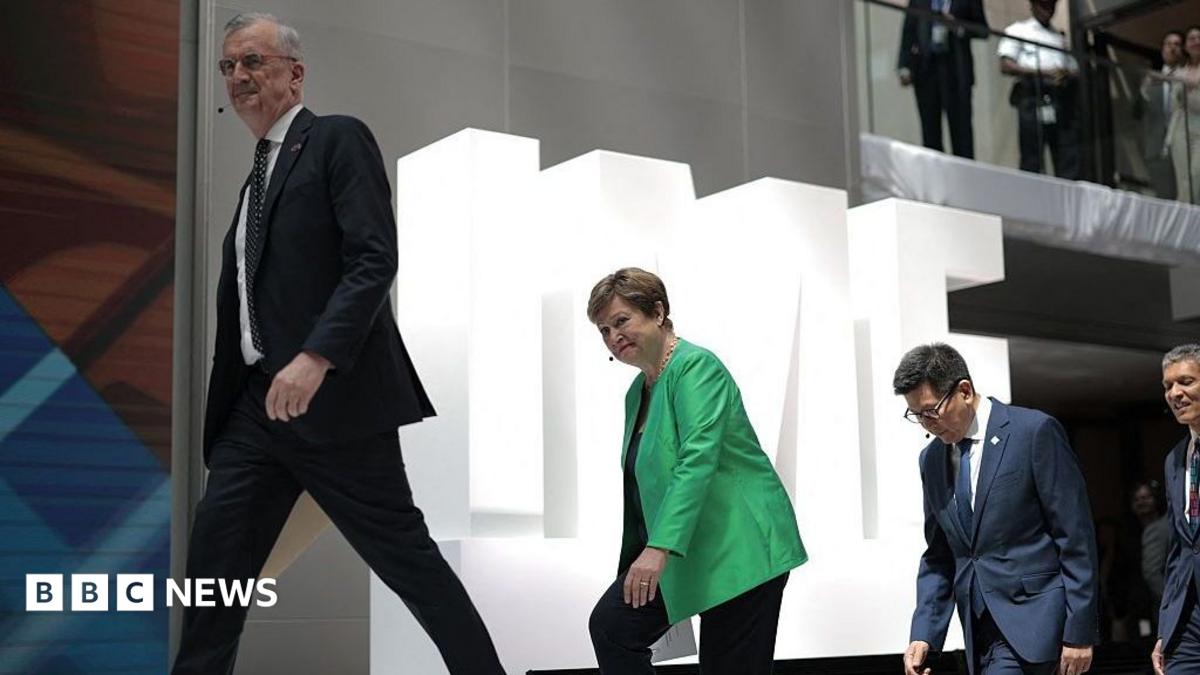
Sovereign balance sheets and corporate technology budgets are moving in conflicting directions across the international financial system. At the International Monetary Fund meeting in Bangkok in October 2026, finance and business leaders confronted macroeconomic conditions defined by sharp divergence rather than uniform recovery. Advanced economies face mounting fiscal pressure from sharply rising interest rate costs, driven by persistent energy supply shocks, unresolved trade conflict, and active war. Concurrently, massive spending on artificial intelligence injects extraordinary capital into computing infrastructure, exerting an opposing upward force against underlying economic deceleration. The resulting friction between fiscal retrenchment and private sector capital deployment complicates standard macroeconomic forecasting across global markets.
This structural tension defined proceedings among policymakers evaluating systemic exposure linked to China alongside rapid technological disruption. Corporate executives frequently argue that massive investments in artificial intelligence provide essential productivity gains capable of offsetting structural stagnation. Yet this corporate narrative meets immediate empirical constraints when evaluated against broader balance-sheet fundamentals. Private capital allocation cannot insulate broader markets from systemic distress while sovereign borrowing costs remain elevated across major economies, including the United States, the United Kingdom, and France. Heavy corporate spending simply cannot offset the drag created by higher sovereign debt service.
Shifting Corridors
Smaller economies have displayed measurable resilience amid fragmented international markets. New trade routes for essential commodities, including oil and gas, were established to bypass geopolitical disruptions and active conflict. Such operational flexibility enabled developing trade hubs to sustain cross-border commerce despite severe geopolitical friction and heightened regulatory barriers. Nevertheless, realigning critical supply chains introduces long-term economic friction. Alternate logistics routes carry structural transport surcharges that compound domestic cost pressures over time, reducing the net margin benefits gained from geographic agility.
Regional supply networks across the Asia-Pacific basin remain deeply exposed to broader policy shifts and persistent trade conflicts involving China and the United States. Tactical adjustments across trade corridors cannot permanently shield developing manufacturing centers from external macroeconomic stress. When advanced economies contend with surging debt service overhead, their capacity to absorb sudden global economic shocks contracts significantly. Policy space tightens, leaving developing trade partners vulnerable to sharp cross-border capital reversals whenever international risk appetites deteriorate.
Defenders of technological expansion maintain an optimistic hypothesis. They contend that the accelerating capital build-up in artificial intelligence will rapidly generate disinflationary efficiencies substantial enough to counteract supply-side shocks and geopolitical turbulence. Under this framework, elevated borrowing costs represent merely a temporary friction for firms capable of securing technological dominance before debt burdens choke operational margins. Proponents argue that computing advancements will stimulate unexpected total factor productivity, dampening the fiscal drag felt across sovereign bond markets.
Structural Constraints
That optimistic projection fails to resolve the structural drag of sovereign liabilities. Software infrastructure cannot retire outstanding sovereign debt obligations, nor does it resolve persistent energy shocks that burden industrial manufacturing bases. Instead, the divergence between speculative capital flows into computing infrastructure and escalating sovereign debt costs creates compounding systemic instability. Financial institutions and regional supply chains operate within the reality of real-economy interest rates, not private market valuations. Technology investments cannot compensate for the rising cost of servicing baseline public sector debt.
Macroeconomic stability over the approaching cycle depends on whether sovereign borrowing costs stabilize before private technology spending experiences fatigue. Finance officials who concluded talks in Bangkok without establishing a framework to reconcile these opposing forces leave regional markets vulnerable to abrupt capital flight. Sustainable global growth cannot rest exclusively on the expansion of corporate computing capacity while sovereign debt burdens escalate and trade conflicts remain unresolved.
Sources
Newsletter
Pacific Daily
A curated briefing from Thailand, Asia-Pacific and the world.