Australia's Fintech Tightrope: Navigating Innovation Amidst Regulatory Scrutiny
As Sydney's fintech scene matures, questions arise about its competitive edge against Singapore and Hong Kong's agile regulatory environments.
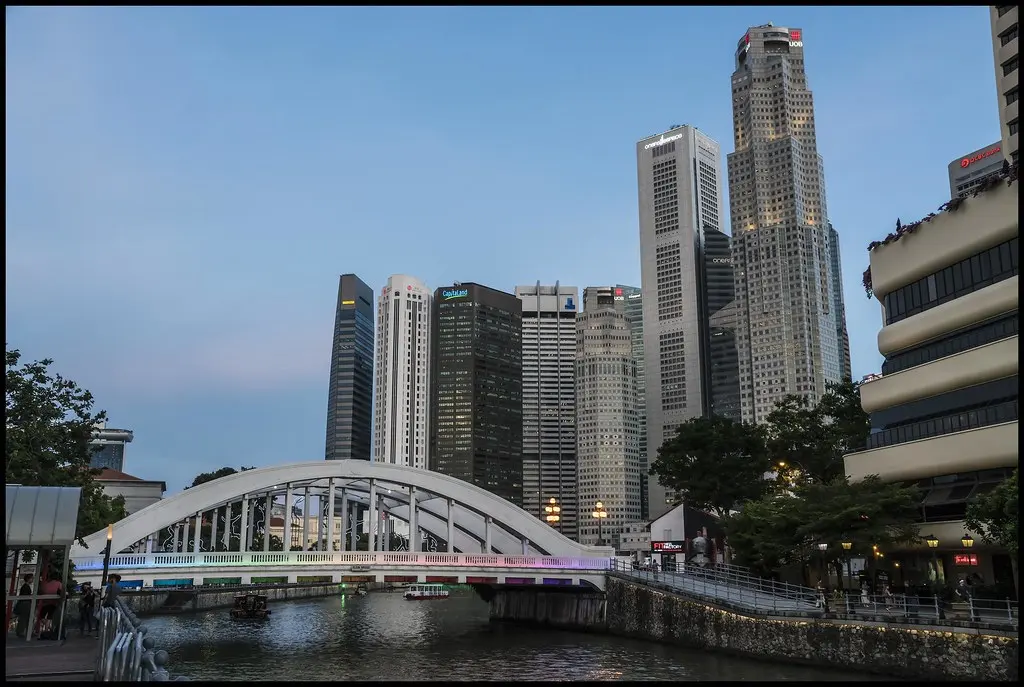
SINGAPORE
SYDNEY — The sun-drenched offices overlooking Sydney Harbour might project an image of effortless innovation, but beneath the surface, Australia's fintech startups are wrestling with a regulatory landscape that often feels more like a minefield than a springboard. Having spent the last few weeks speaking with founders, investors, and policymakers across the continent, it's clear that while Australia boasts a robust financial sector and a digitally savvy population, its approach to fintech regulation is increasingly under scrutiny, particularly when compared to the nimble frameworks championed by regional rivals Singapore and Hong Kong.
My conversations, from a bustling co-working space in Barangaroo to a quiet coffee shop in Melbourne’s CBD, consistently circled back to a perceived tension: the desire to foster innovation clashing with a deeply ingrained, prudential regulatory culture. The Australian Securities and Investments Commission (ASIC) and the Australian Prudential Regulation Authority (APRA) are, by all accounts, highly respected regulators globally for their stability-focused mandates. However, this strength, in the context of rapidly evolving fintech, can become a bottleneck.
"The intention is good, no one disputes that ASIC wants to protect consumers and maintain market integrity," remarked Sarah Chen, CEO of a burgeoning RegTech firm, over a virtual coffee. "But the speed at which new products can get to market here, especially if they touch on complex licensing, is visibly slower than what we see our counterparts achieve in Singapore's sandbox. It's a 'prove-it-first' mentality that stifles experimentation." This sentiment echoes a recent report by KPMG, which, while praising Australia's overall financial services strength, subtly highlighted the 'extensive' nature of its regulatory oversight as a potential drag on new entrants.
Australia’s regulatory sandbox, introduced in 2016, was initially hailed as a step forward, allowing companies to test certain financial services for up to 12 months with limited exemptions. Yet, its uptake has been modest compared to the more expansive and iterative sandboxes offered by the Monetary Authority of Singapore (MAS). A founder I spoke with, who recently pivoted his payment startup towards Southeast Asia, pointed out that the Australian sandbox's strict eligibility criteria and limited scope for exemptions meant it often felt like a 'lite' version of full compliance, rather than a truly experimental space. "We ended up spending more time clarifying what we couldn't do than actually building and testing," he recounted, frustration evident.
This isn't to say Australia is without its merits. The Australian Consumer Law offers strong protections, building trust in financial services, and the country’s high digital literacy provides a fertile ground for adoption. The introduction of the Consumer Data Right (CDR) through Open Banking is a significant step towards data portability and competition, an area where Australia is arguably leading some regional peers. However, the phased rollout of CDR, beginning with major banks and slowly expanding, has been a careful, almost cautious, dance, rather than an explosive leap.
"We need to shift from a 'how can we stop it' mindset to 'how can we safely enable it'. The global race for fintech dominance isn't waiting for us to finish our paperwork."
Comparing Australia to Singapore is particularly instructive. Singapore's MAS actively promotes a 'Fintech Festival' and fosters an ecosystem where regulators often act as facilitators. Their regulatory frameworks, like the Payment Services Act, consolidate various payment activities under a single license, simplifying market entry. Hong Kong, too, despite its recent political headwinds, has demonstrated a pragmatic approach to virtual banking licenses and digital asset regulation, often moving with greater agility to capture emerging opportunities.
The Talent Drain Dilemma
One concerning observation from my Sydney visits is the subtle but growing 'brain drain' of fintech talent. Several entrepreneurs mentioned that while Australia is an excellent place to start a company due to its strong economy and access to early-stage capital, scaling often means looking offshore. "The compliance burden and the slower path to market means that Series A and B funding rounds often come with the implicit understanding that growth will likely accelerate in a more permissive jurisdiction," explained a venture capitalist friend over lunch. This suggests that while Australia cultivates innovators, it struggles to retain them at critical growth junctures.
A Path Forward?
Australia's strong foundations – a skilled workforce, robust financial infrastructure, and a trusted legal system – are undeniable assets. The challenge lies in adapting its regulatory approach to match the pace of technological change. A more collaborative, outcomes-focused dialogue between ASIC/APRA and the industry, perhaps emulating MAS's proactive engagement, could unlock significant potential. Streamlining licensing pathways, offering clearer guidance for emerging technologies like Web3, and genuinely expanding the scope and flexibility of regulatory sandboxes would signal a serious commitment to global fintech competitiveness. Otherwise, Sydney risks becoming a fertile ground for ideas that ultimately flourish elsewhere, leaving Australia to play catch-up in a race it once seemed poised to lead.
Newsletter
Pacific Daily
A curated briefing from Thailand, Asia-Pacific and the world.