Financial Literacy Mandates: A Question of Implementation, Not Intent
Hawai‘i's new requirement for financial education presents a model for the Asia-Pacific, but the challenge lies in measurable effectiveness.
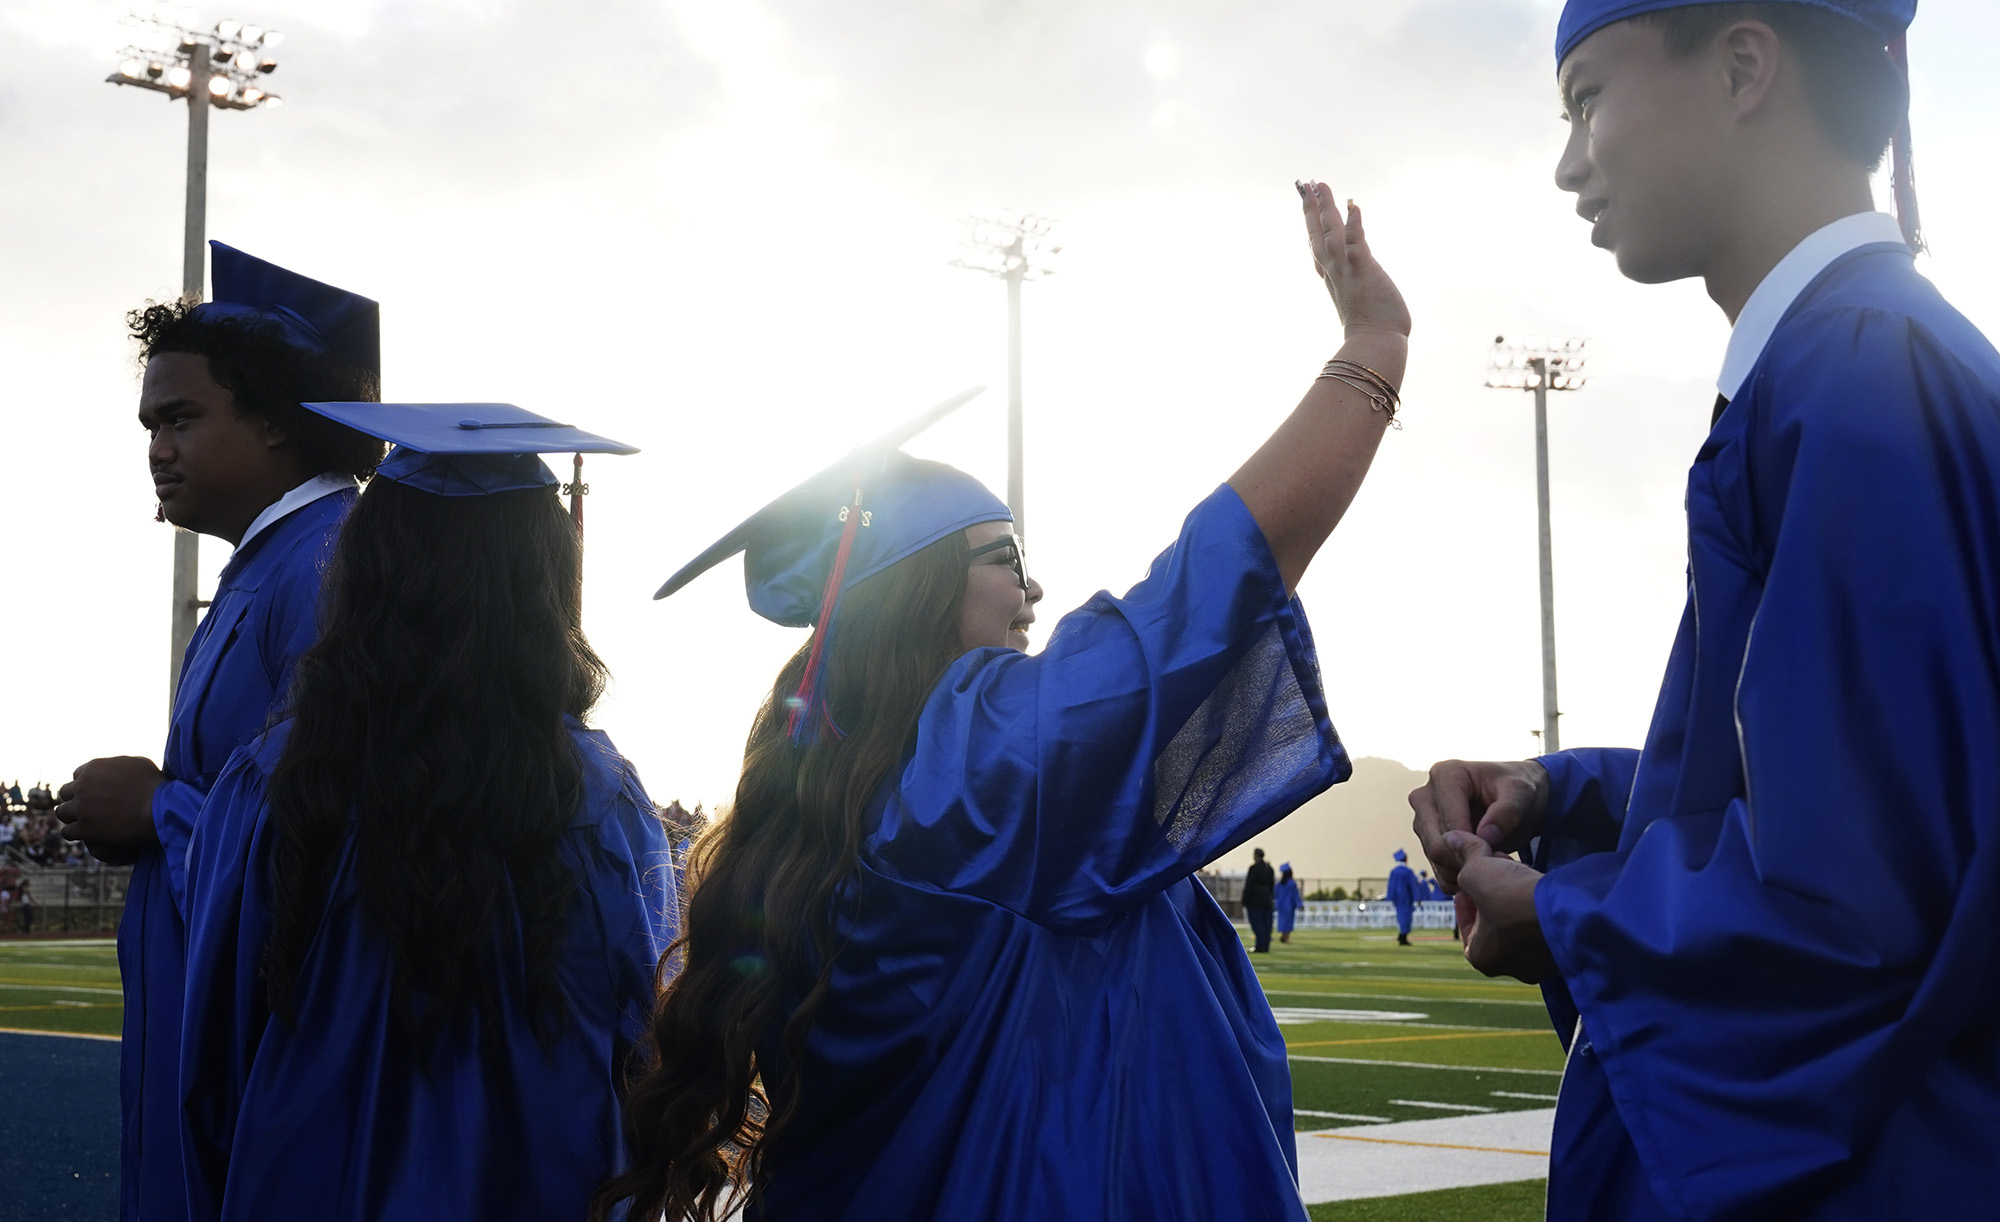
Hawai‘i's education department is requiring financial literacy lessons for its graduates, a policy decision reported on August 28, 2026, following two decades of advocacy from lawmakers and educators. The intent behind such a mandate is clear: to equip students with fundamental financial skills. However, the critical question for any jurisdiction considering similar measures, particularly across the Asia-Pacific, shifts from the 'what' to the 'how' and, more importantly, the 'how effectively'.
For Hawai‘i, the Honolulu Civil Beat noted that implementation and effectiveness "may vary." This qualification highlights a key limitation in such educational mandates. Pearl City High School teacher Tammy Yoon is reported to be teaching the basics of personal finance, including how to write a check and calculate. While these are foundational skills, the scope and depth of "financial literacy" can differ significantly. Without standardized metrics for skill acquisition and quantifiable outcomes, the actual impact of such programs remains an open question.
The Asia-Pacific region, characterized by diverse economic landscapes and varying levels of financial inclusion, could draw lessons from Hawai‘i's experience. Nations considering financial literacy mandates must develop robust frameworks for curriculum development, teacher training, and, crucially, performance evaluation. The absence of such frameworks risks transforming a well-intentioned policy into an administrative requirement with unclear returns on investment. The reported two decades of advocacy suggest a persistent belief in the value of this education, but a belief does not equate to a guaranteed outcome without rigorous design and execution.
One potential counterargument is that any financial education is better than none. This perspective holds merit in principle, particularly given the increasing complexity of personal finance in modern economies. Proponents might argue that even basic exposure to concepts like budgeting or debt management provides a beneficial foundation. However, the absence of clear metrics for assessing learning and behavior change means that such an argument relies on assumption rather than demonstrated impact. A partial or poorly delivered curriculum could create a false sense of security or fail to address the actual financial challenges graduates will face.
Implementing financial literacy effectively requires a sustained investment in resources beyond mere policy declaration. This includes developing up-to-date curricula that reflect current economic realities, ensuring educators are adequately trained and supported, and establishing mechanisms to track student comprehension and application of financial principles over time. Without these investments, the effectiveness of Hawai‘i's new requirement, and any similar initiative in the Asia-Pacific, will remain largely unquantified, leaving the precise benefits to future graduates a matter of conjecture rather than verifiable data.
Sources
Newsletter
Pacific Daily
A curated briefing from Thailand, Asia-Pacific and the world.