When Retirement Savings Are Asked to Build the State
Forum discussions in Bangkok urge deploying pension capital into domestic economies, but developmental mandates risk overriding fiduciary discipline without strict institutional governance.
SINGAPORE
A family compound along a central Thai canal once managed aging through physical proximity: timber floorboards shared among three generations, rice jars filled from communal harvest, and the quiet expectation that younger hands would repair roofs and tend sickbeds without formal paperwork. Security was an accumulation of filial custom rather than financial yield. When wage employment drew workers into urban factories and civil service desks, that domestic compact gradually dissolved into statutory deductions, converting intimate kin obligations into distant ledger entries held by state pension funds.
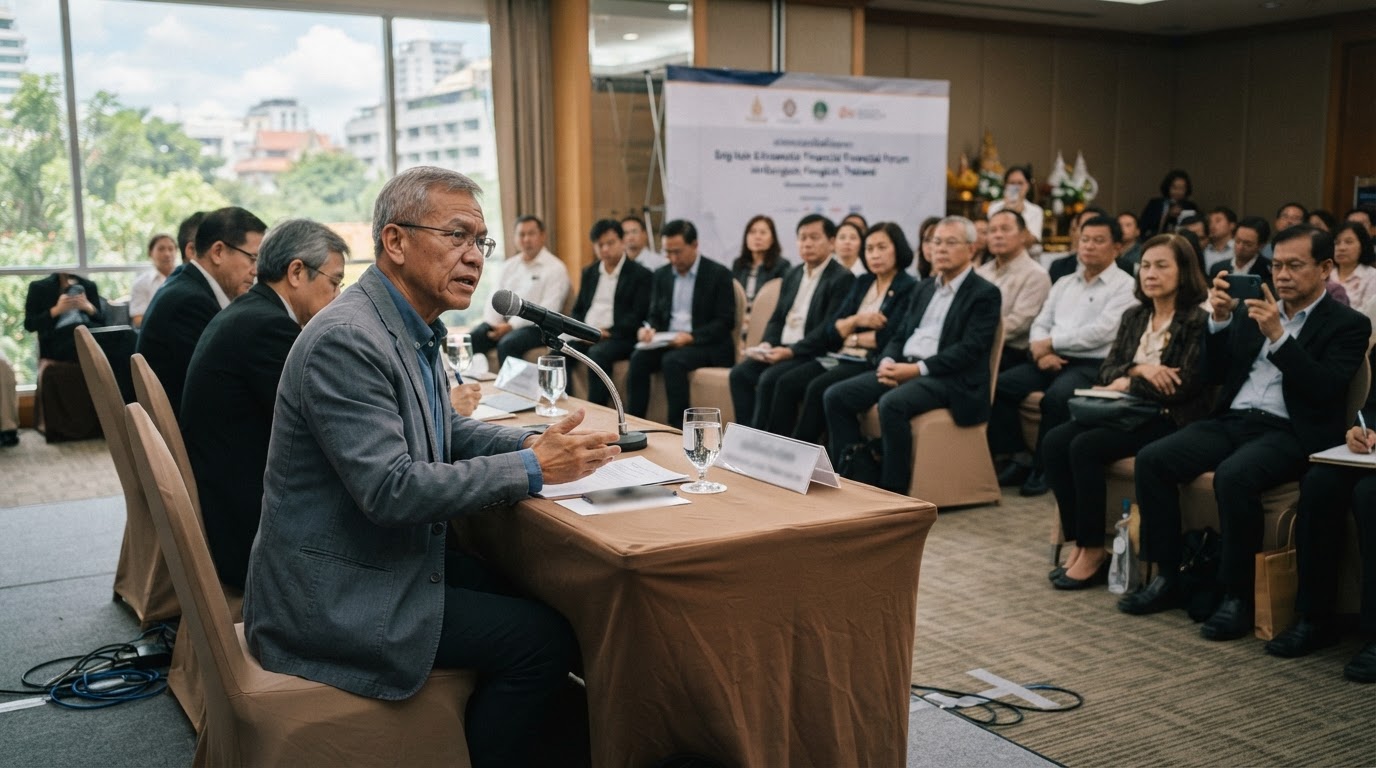
In Bangkok, that institutional bargain is being recalibrated. Forum speakers recently gathered to insist that pension reforms must protect retirement savings while directing capital into domestic economies. Sound governance and returns for members, they maintained, must remain top priorities.
The proposition sounds reasonable on conference floors, yet it subtly redefines what a retirement reserve is designed to do. For decades, modern retirement programs in Thailand offered a clear pledge to civil servants and private wage earners: their monthly withholdings would be insulated from local political ambition, managed under strict fiduciary standards, and preserved until old age. Asking these funds to double as engines for domestic development alters that covenant. The state ceases to be merely a dispassionate custodian of accumulated wages; instead, national planners begin eyeing member liquidity as a convenient pool of domestic finance, balancing fiduciary duties against political projects.
The Dual Mandate
Proponents of domestic deployment argue that retirement capital cannot thrive in isolation from the national economy that sustains its contributors. Capital channeled into local infrastructure, utilities, or enterprises can stimulate local employment and expand the tax base. Forum participants, echoing perspectives discussed alongside World Bank meetings, emphasize that domestic investment can generate reliable yields if institutional capacity is robust. Under ideal oversight, contributors might gain twice: enjoying steady returns while living within a country whose roads, power grids, and businesses were fortified by their own savings.
That alignment assumes benevolence and flawless foresight. When statutory mandates compel funds to favour home markets, financial discipline easily yields to domestic political pressure, pressuring fund managers to accept lower returns or absorb domestic market volatility to rescue struggling domestic enterprises.
Pension reforms should protect retirement savings while allowing funds to invest in domestic economies.
Across the Asia-Pacific, where rapid demographic aging is compressing working-age populations, the margin for error in retirement management has vanished. Societies that once relied on expansive kin networks now depend on formal institutions to prevent elderly poverty. Forum discussions addressing pension fund reforms alongside World Bank frameworks acknowledge that good governance is the sole bulwark against capital erosion. Without independent trustees and transparent fiduciary thresholds, domestic investment policies risk turning civic retirement savings into captive liquidity for state planners, subordinating individual old-age security to broader macroeconomic intervention.
Preserving the Fiduciary Covenant
The central question behind pension reform is not merely financial but cultural: what is preserved, and what is quietly being replaced? Historical arrangements in the canal compound were sustained by direct, face-to-face accountability, where obligations could not be deflected to distant committees. Modern pension systems replaced that kinship web with an institutional promise of technical neutrality and fiduciary care. If funds are now directed toward domestic economic agendas without impeccable governance, that replacement falters. Workers trade the tangible protection of the family courtyard for speculative balance sheets, leaving ordinary pensioners to shoulder the consequences.
Sources
Newsletter
Pacific Daily
A curated briefing from Thailand, Asia-Pacific and the world.