Credit Card Campaigns Prioritise Transaction Volume Over Consumer Solvency
Bank Rakyat's new credit card campaign, offering a holiday prize, illustrates a regional financial services strategy that incentives spending, with inherent risks for individual cardholders.
SINGAPORE
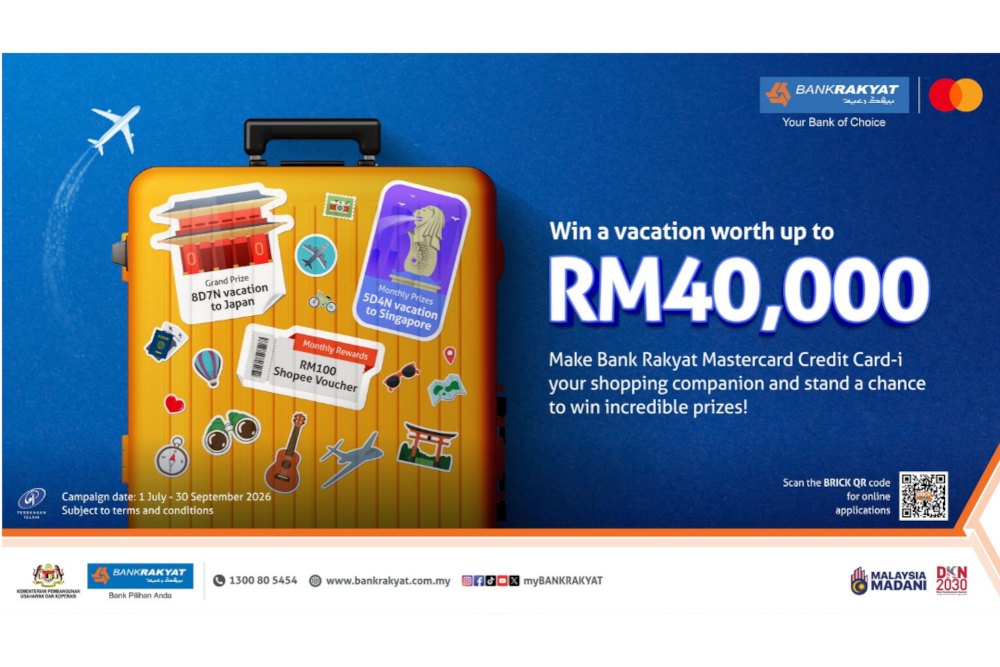
Bank Rakyat launched its 'Mastercard Credit Card Spend Bonanza' campaign on 2026-09-18, advertising a chance to win a holiday valued at RM40,000. Such promotions are a recurring feature in the financial services sector, designed to increase credit card activity. The structure of these campaigns typically rewards higher transactional volume or frequency, directly linking increased spending to improved odds of winning. This mechanism fosters immediate activity for the issuing bank but can contribute to higher outstanding balances for consumers.
The stated aim of the campaign is to boost Mastercard credit card usage. While the precise qualification criteria for participants are not detailed, the term 'Spend Bonanza' implies that greater spending is the primary pathway to entry. This approach reliably generates quantifiable transactional activity for the bank. For consumers, the prospect of a high-value prize, such as a RM40,000 holiday, is positioned as a significant draw. However, the value of this inducement for a limited number of winners must be assessed against the broader financial implications for the collective pool of participants.
From the bank's perspective, the strategic incentive is straightforward: an increase in credit card transactions generally leads to higher interchange fees. More critically, elevated transaction volumes often result in a greater number of cardholders carrying balances month-to-month. When balances are carried, interest accrues, which constitutes a substantial revenue stream for financial institutions. The cost associated with the RM40,000 holiday is a marketing expenditure, a calculated investment intended to generate returns through increased transaction volumes and potential interest income. This business model is prevalent across the Asia-Pacific region, where the growth of consumer credit metrics frequently serves as a key performance indicator for many banks.
The immediate effect of such campaigns is typically an observable rise in consumer spending. For Bank Rakyat, this fulfills the campaign's stated objective. The implicit assumption is that a sufficient number of cardholders will either increase their discretionary spending or consolidate existing spending onto their Bank Rakyat Mastercard to participate. However, this induced spending does not inherently equate to an improvement in cardholders' financial well-being. Conversely, if the stimulated spending leads to balances that are not paid in full, it contributes to an increase in personal debt.
Disparity in Outcomes
A fundamental tension exists between a bank's objective to maximise transaction volume and the potential for increased consumer indebtedness. While an RM40,000 prize may appear substantial, it is awarded to a select few winners. The majority of participants will incur additional spending without receiving any direct benefit beyond the transactional utility. This uneven distribution of reward means the broad base of cardholders is incentivised to spend, thereby providing a collective benefit to the bank, while the individual risk of increased debt largely rests with the consumer.
A counterargument suggests that consumers who manage their finances responsibly will only use credit cards for expenditures they can promptly repay, irrespective of promotional offers. This perspective posits that such campaigns primarily reallocate existing spending rather than generate new, potentially unsustainable debt. However, the 'bonanza' framing explicitly encourages additional spending, often beyond typical consumption patterns, to maximise entry chances. This psychological inducement can override disciplined budgeting for some individuals, leading to balances that are not settled completely, and consequently incurring interest charges. The incentive structure does not distinguish between a cardholder capable of prompt repayment and one who may encounter difficulties; it rewards spending universally.
The limitations in fully assessing the campaign's impact are evident, as specific metrics regarding average balance increases, default rates, or the total number of participants are not available. Without these figures, the precise yield assumption for Bank Rakyat cannot be completely quantified. Nevertheless, the practice of incentivising short-term transactional surges through high-value prizes is a well-established strategy in the region. The ultimate financial outcome for individual consumers hinges on their personal financial discipline, set against the backdrop of widespread promotional inducements to spend. The long-term implications of encouraging this type of credit usage for the overall consumer financial health within the Asia-Pacific region remain an unresolved consideration.
Sources
Newsletter
Pacific Daily
A curated briefing from Thailand, Asia-Pacific and the world.