Apple Tests the Ceiling of Consumer Hardware Pricing
The arrival of the iPhone Duo establishes whether premium device margins can absorb rising component pressures across Asia
SINGAPORE
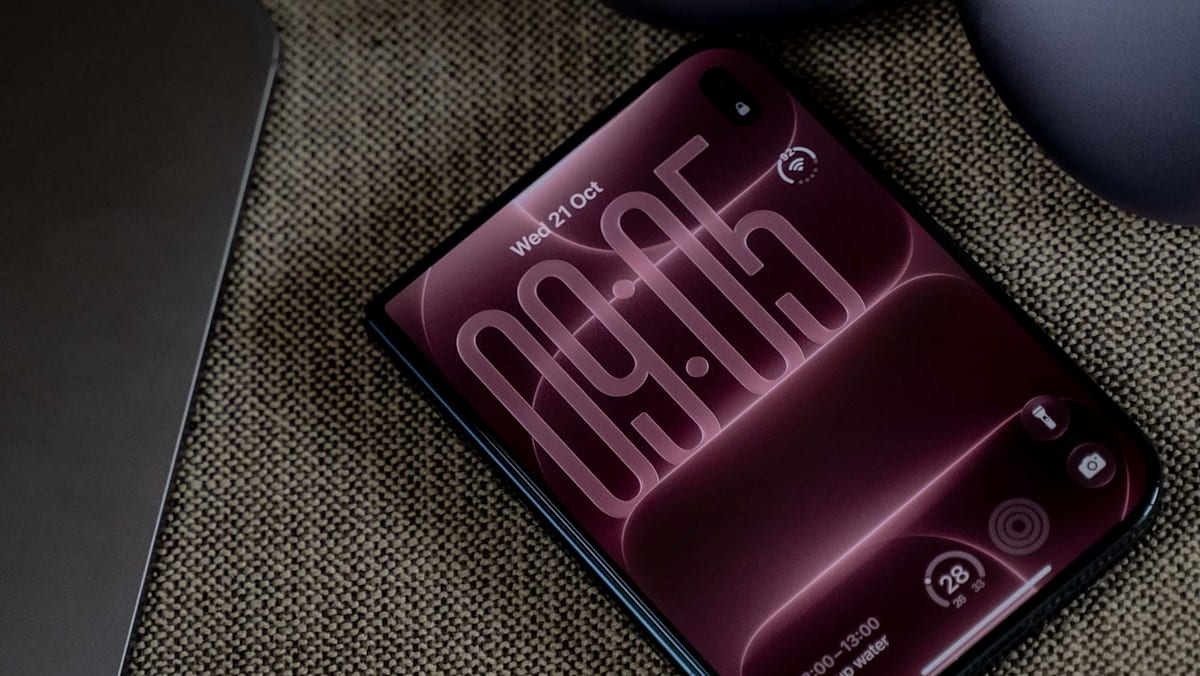
Hardware pricing rarely moves in isolation from industrial margins. When Apple positions its first foldable device, the iPhone Duo, at a baseline price of S$3,099, the figure registers as more than an ambitious retail benchmark for Singapore. It marks a deliberate test of how much capital affluent consumers will surrender to subsidise higher fabrication hurdles.
Foldable architecture alters the unit economics of premium consumer electronics. The device integrates an external 5.4-inch screen alongside an internal 7.6-inch OLED panel, producing an active surface that expands by 50 per cent when unfolded. Driving this hardware is the A20 Pro silicon, engineered to handle sustained computational loads across split displays. Yet packaging flexible displays and specialised internal hinges introduces structural manufacturing yields that remain significantly harsher than standard chassis assembly. Rather than absorbing the higher industrial attrition internally, Apple has transferred the expense directly into consumer tiering, pushing retail thresholds to US$1,999 in international markets and S$3,099 in Singapore.
Shifting Production Math
This pricing calculus emerges alongside broader operational recalculations across hardware lines. Rising memory costs earlier triggered price increases across MacBooks and iPads, demonstrating that component inflation cannot simply be offset by existing operational scale. Concurrently, selective manufacturing adjustments—such as shifting certain Mac Mini production to Houston from assembly footprints in Asia—underscore how geographical reorganisations complicate operating budgets. Every supply line realignment adds logistical friction, and the accumulated costs eventually surface on retail shelves.
For regional electronics manufacturing ecosystems across Asia, the commercial trajectory of the iPhone Duo delivers a critical signal. Advanced panel suppliers and micro-component specialists rely on volume adoption to bring down the steep depreciation curves of flexible OLED machinery. If elevated retail hurdles constrain adoption to a narrow cohort of affluent buyers, production yields improve at a sluggish pace. Conversely, if Apple maintains consumer demand despite the steep ticket size, competitors face renewed pressure to justify their own hardware pricing structures across comparable product categories.
Consumer Friction and Market Limits
Sceptics argue that establishing an ultra-premium tier risks dampening turnover. Consumer replacement cycles have extended across major markets, and stretching price points well beyond standard flagship models could turn foldable hardware into an enduring niche rather than an eventual mass standard. Buyers weighing an upgrade from an iPhone 18 Pro or Pro Max may decide that an outer screen and an expansive internal display do not warrant twice the capital commitment of conventional mobile hardware, especially when basic productivity tasks are already handled competently by standard flagships.
That hesitation is rational, but it underestimates how platform ecosystems extract commercial rent from high-income demographics. By anchoring the device at the apex of its catalogue, Apple reinforces its hardware hierarchy, preserving elevated gross margins while testing exactly where elasticity breaks. The commercial reality of advanced hardware no longer hinges solely on consumer curiosity or screen real estate. The decisive contest depends on whether production efficiencies can catch up with retail inflation before consumer tolerance expires entirely.
Sources
Newsletter
Pacific Daily
A curated briefing from Thailand, Asia-Pacific and the world.